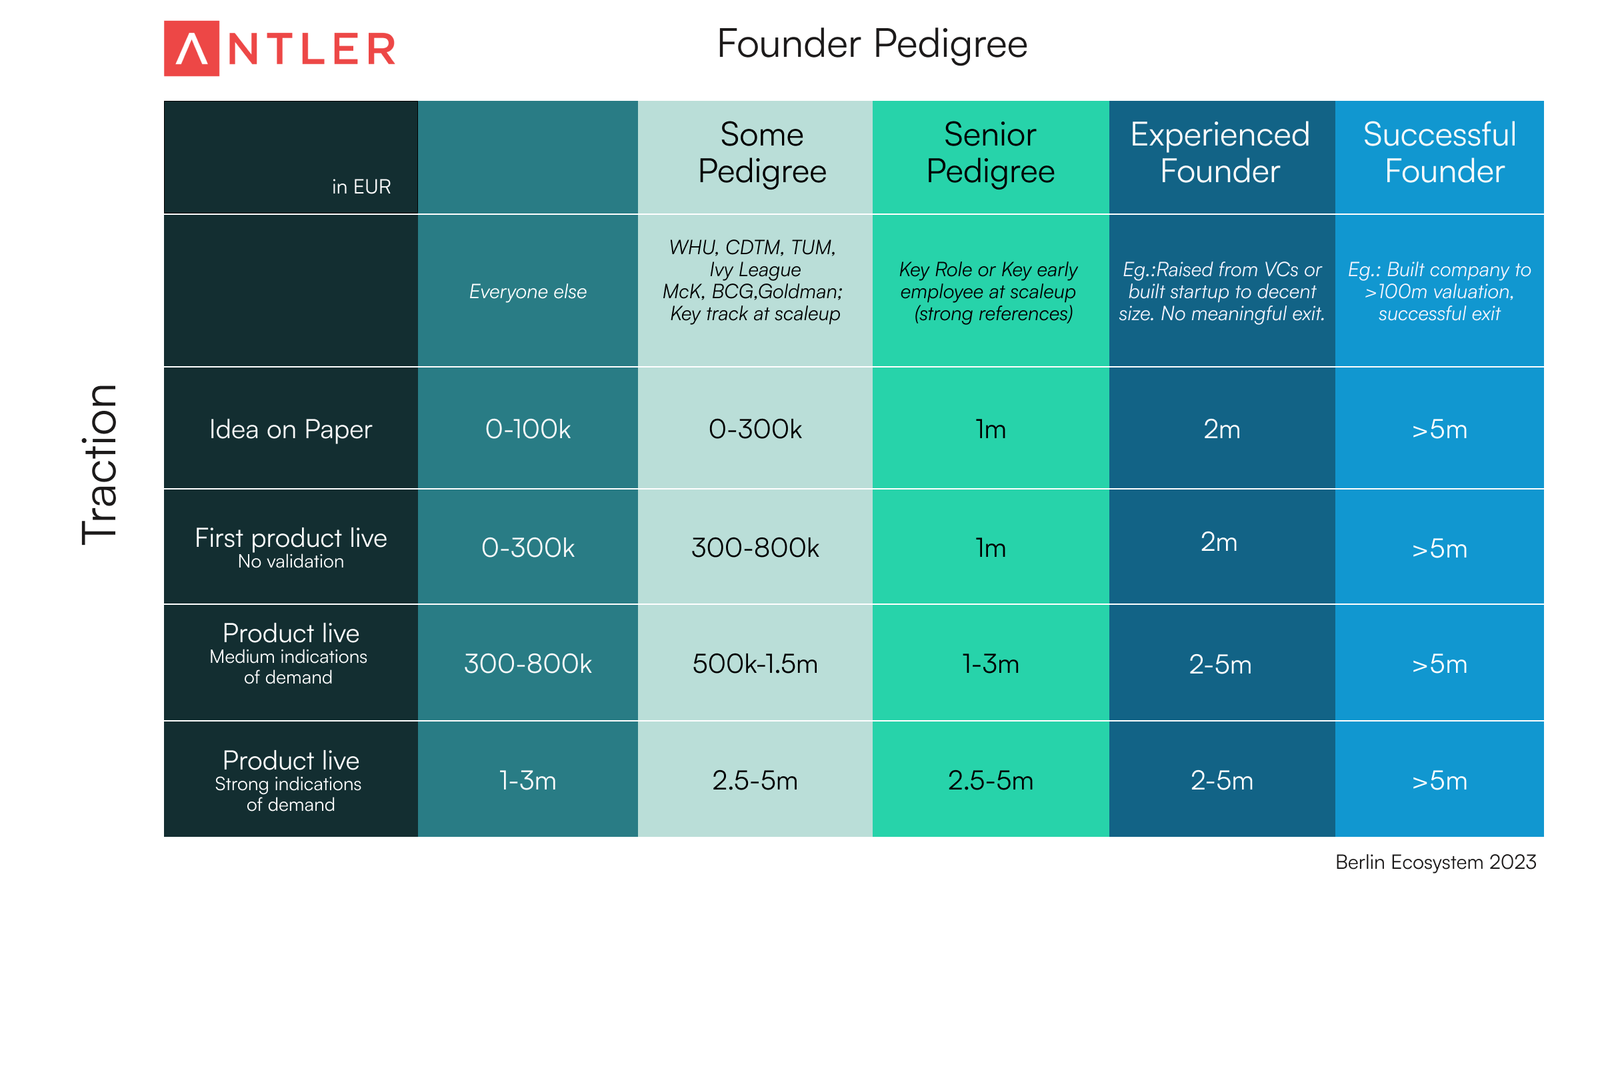
Two dimensions matter: Founder Pedigree & Traction
The two dimensions that I believe matter at this early stage are “Founder Pedigree” & “Traction”.
The less traction, the more founder pedigree matters: In later fundraising rounds it is mostly about business performance, and the “science” behind the business - think Christoph Janz’s SAAS fundraising napkin. However, when there are no numbers to look at, investors look at the founders' past to assess whether they believe the founders can deliver in the future.
It is about limiting execution risk: Someone who has built a company before successfully is far less likely to fail at shipping a first product, hiring a team, etc. than someone who has not. And someone who has gone to a university that produces lots of successful founders seems statistically more likely to build a successful startup than someone who did not.
This isn’t necessarily rational: Great founders get overlooked all the time because they do not fit the pattern of what a successful founder typically looks like. That is not necessarily rational but in the face of thousands of similar-looking investment opportunities, it is a real filter function for investors.
Traction beats pedigree: When a founder presents something more than an idea on paper and the product has gained some traction, the ability to raise will increase depending on how big the traction is and in which stage the product is. A lower-profile founder will be able to raise when the idea is not only an idea anymore. Indeed there are lots of examples of founders without the “classic” backgrounds who have built awesome companies, they just need to prove more in the beginning.
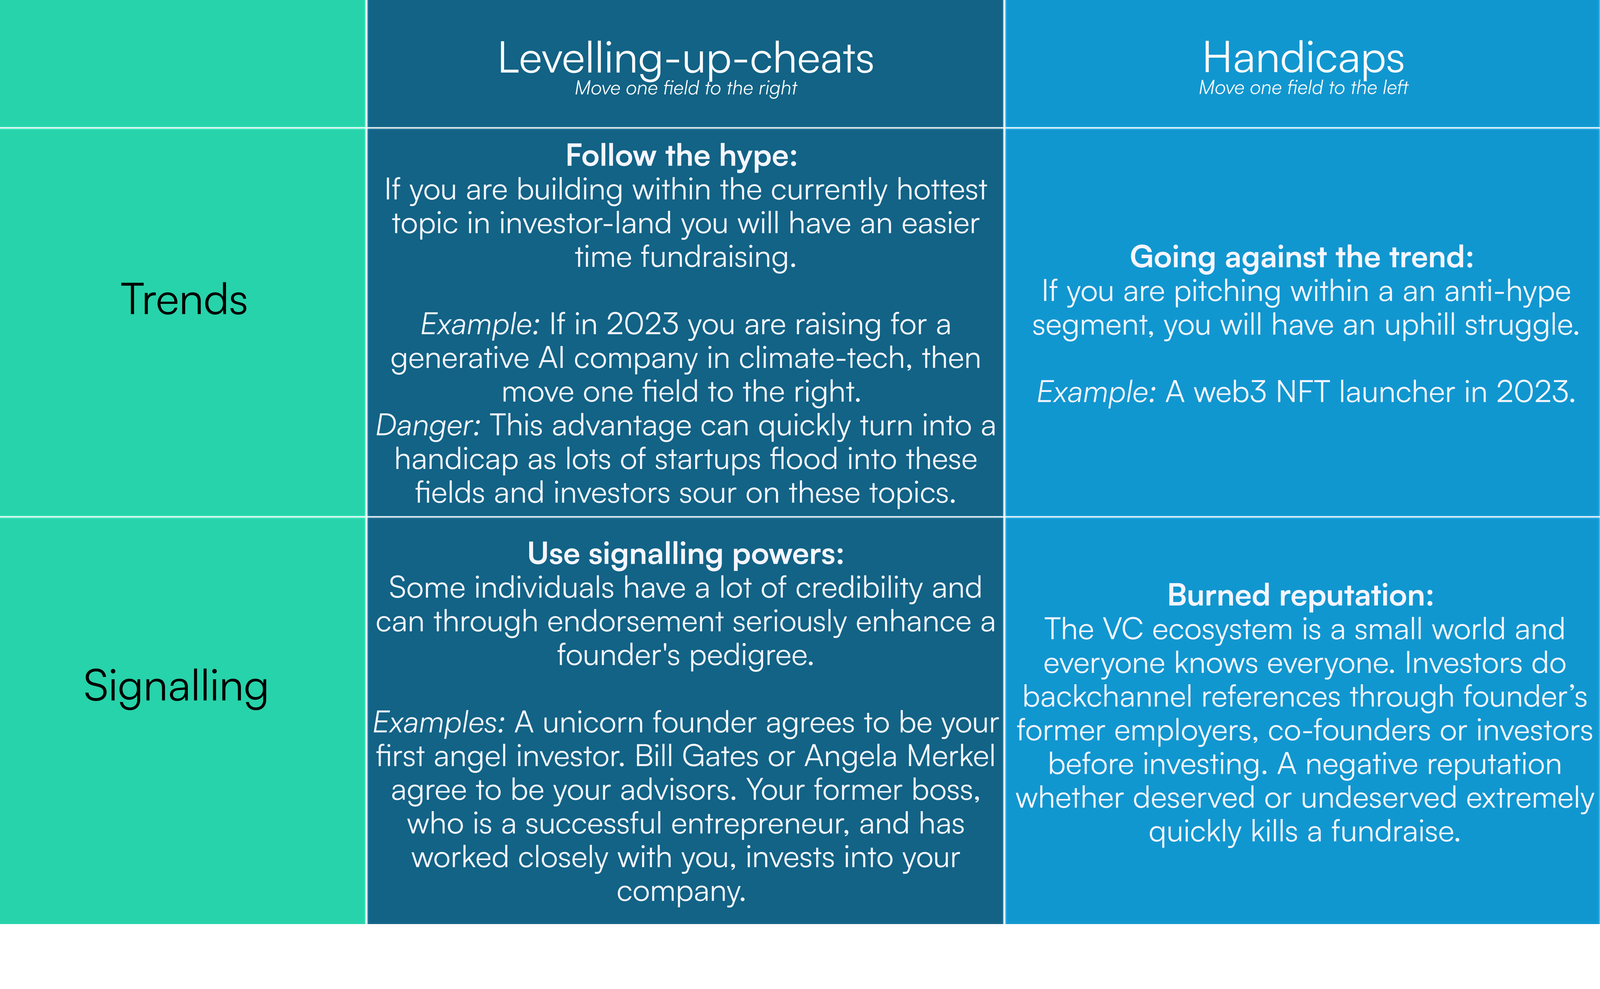
Levelling up cheats & Handicaps
There are some factors which change the game. “Levelling up cheats” will move the founder one field to the right; “Handicaps” will move the founder one field left.
Prerequisites
There are a few necessary prerequisites without which a founders will not be able to raise, no matter the pedigree or traction:
Prerequisite #1 Fundraising-ability: All of this is built on the assumption of the founder having reasonable fundraising skills. There are plenty of founders who even with reasonable pedigree and traction are unable to raise a single cent, simply because they are not good at fundraising. Networking, sales skills, storytelling, running a tight process, etc. - are a must-have to raise. Some teams will be able to raise much more than the cheat sheet suggests since they are fundraising gods while many successful founders who are not good fundraisers, need to survive longer on ramen noodles and get to a point where the numbers talk for themselves.
Prerequisite #2 Market attractiveness: The matrix assumes a significant market size and attractive market exists. At this stage this is probably binary: either the market is attractive and a team can raise or it is not. A team will not be able to raise 2x the money at this stage simply because the market size is 40bn EUR instead of 20bn EUR, it is more a question of whether investors can get excited about the opportunity at all.
Practical considerations
Valuations are a function of capital raised: By and large, the market will assume that the amount you are raising is the maximum amount you are able to raise. The same factors that govern your ability to raise govern your company valuation. Hence as a rule of thumb: assume 15-25% dilution irrespective of the amount of capital raised. i.e., a team raises 800k, then likely the valuation will be 3.2m - 5.3m.
LinkedIn profile beats pitch deck: One thing most founders underestimate: In the very early stages LinkedIn profiles may very well be more important than the actual pitch deck. Many investors will look at a founder's LinkedIn profile before they decide whether to take a first meeting or even take a closer look at a pitch deck.
When is this wrong? (Disclaimers)
Numbers are purely directional: I have bounced and validated them with a fair number of experienced investors in the ecosystem over the past year and there is general agreement, but the numbers in the different fields will never be exact.
Non-Software: This by and large is modelled on software start-ups. For Biotech & Hardware companies different rules apply in many ways.
Copycat models: Copycat models tend to be very binary. Usually, a number of very experienced teams are able to attract very large amounts of funding since the “business model risk” is much less. Other teams or teams that are late to the party are usually completely unable to raise. Often a path to building these businesses more slowly simply does not exist.
Raising from a rich uncle: If most of the money comes from friends and family who are not experienced venture investors, different rules apply.
Do you have thoughts on this topic or additional ideas on how to make this framework better? Reach out to me directly on: alan@antler.co.